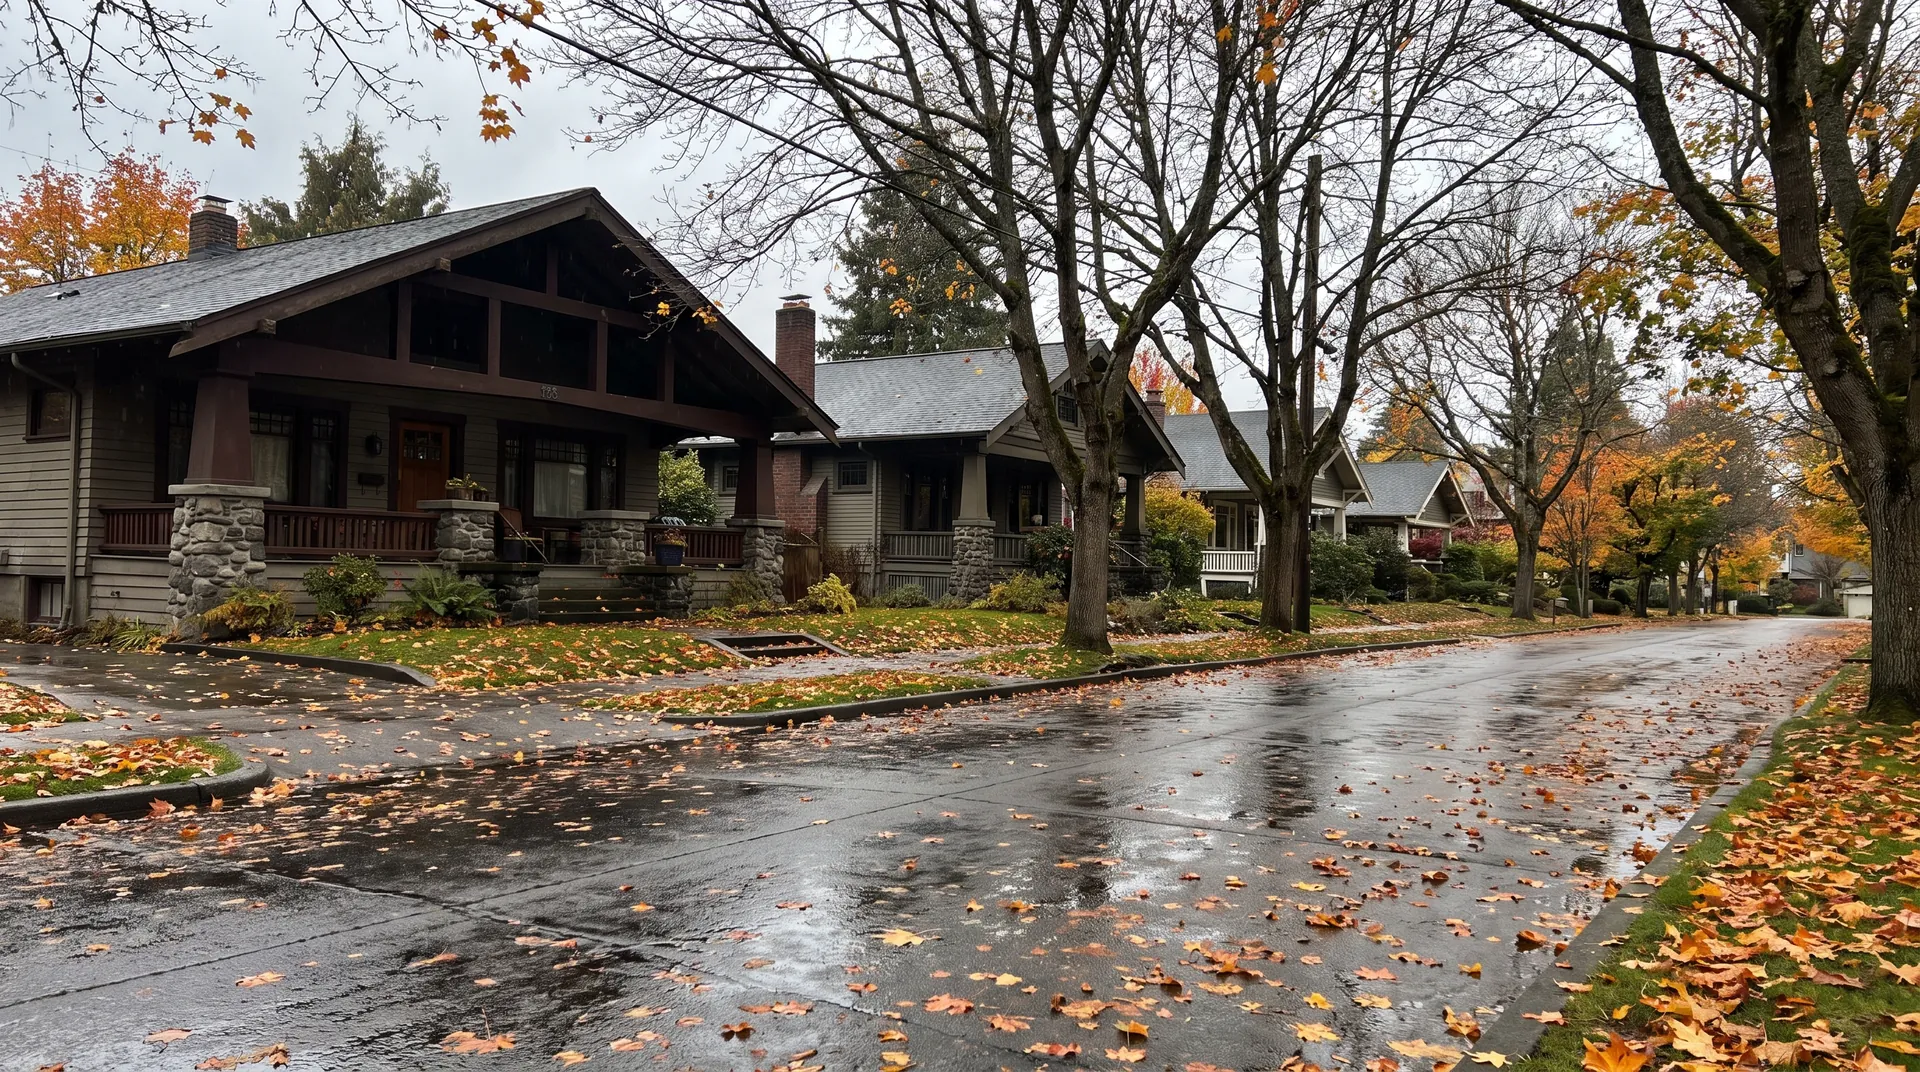
Seattle
Home insurance in Seattle
Seattle's homeowners policies are shaped by the age of its houses. Many neighborhoods are full of homes built before 1940 — beautiful, and expensive to rebuild to modern code. Add steep slopes, older sewer lines and the Seattle Fault, and the details of a Seattle policy matter more than the price.
Insuring an older Seattle home
Short answer: Insurers will ask about wiring, plumbing, heating and the roof. Updates help; original knob-and-tube wiring or galvanized plumbing can limit options until replaced.
- Ordinance or law coverage pays the extra cost of rebuilding to current code — critical for older homes
- Replacement cost on a craftsman with original millwork can be far above a tract home of the same size
- Oil tanks: older homes may have a decommissioned or buried heating-oil tank; disclose it and know how it's treated
Slopes, sewers and the Seattle Fault
Short answer: Seattle's mapped landslide-prone slopes, older combined sewer areas and the Seattle Fault create three exposures a standard policy handles narrowly or excludes.
Steep slopes
Earth movement, including landslides, is excluded from standard homeowners policies. Know before you buy on a mapped slope.
Sewer backup
Older sewer systems overwhelmed by heavy rain can back up into basements. It takes an endorsement to cover it.
Earthquake
The Seattle Fault runs east–west beneath the city. Earthquake coverage carries a percentage deductible — choose it deliberately.
Seattle condos and renters
Short answer: Many Seattle households own condos or rent; both need their own policy type.
See condo insurance (HO-6) and Seattle renters insurance. Chett's team serves Seattle by video and phone, and in person in Federal Way.
Frequently asked questions
Is home insurance more expensive in Seattle?
Seattle's high rebuild costs and older homes push dwelling limits up, which raises premiums. Accurate limits and documented updates keep it fair.
Does homeowners insurance cover knob-and-tube wiring?
Coverage isn't about the wiring itself — it's whether a carrier will write the home. Some won't until it's replaced; others will with conditions.
Sources
- Washington DNR — Geologic hazard maps (landslides, faults)
- FEMA Flood Map Service Center — look up your address
Explanations on this page are general. Your policy documents control what is and isn't covered.
Keep exploring
- Home insuranceWhat Washington homeowners insurance covers — dwelling, belongings, liability, living costs — and what it doesn't. Get a home insurance quote from a Federal Way agent.
- Condo insurance (HO-6)Condo insurance (HO-6) covers your unit's interior, belongings and liability, plus loss assessments from the HOA. What the HOA master policy covers — and what it leaves to you.
- Seattle renters insuranceSeattle renters insurance for city life: bike and car-prowl theft, older brick buildings and earthquake coverage for belongings, storage units, roommates and lease requirements.
- Earthquake insurance in WashingtonStandard Washington homeowners policies exclude earthquake. How earthquake endorsements work, percentage deductibles, and how to decide for a Puget Sound home.
- RentonRenton home insurance for Highlands ramblers, Kennydale lake-view homes and newer townhomes: slopes, Cedar River flooding, HOA townhome coverage and earthquake.
- Federal WayHome insurance in Federal Way from a local agent who has served the community for 25+ years. Bluff and tree risks, older split-levels, flood and earthquake — and a team you can visit.
Ready when you are
Get a real quote from a real person.
Two minutes online. A person from the team follows up — typically the same business day — and walks you through options side by side.